
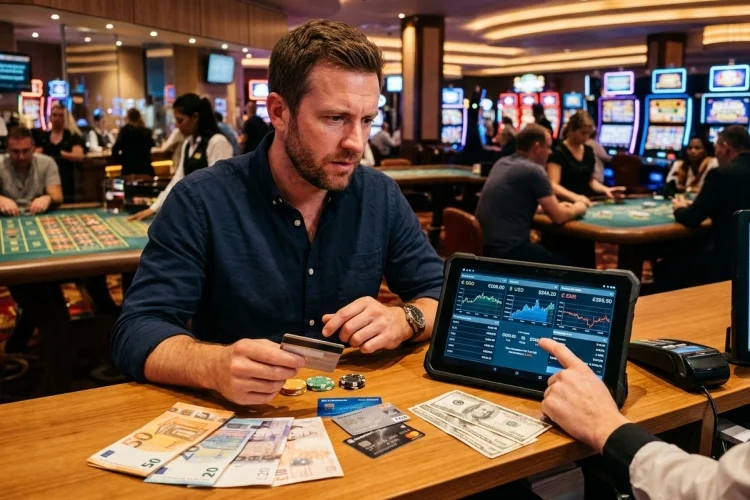
A casino deposit can look simple until the account, bank card, and payment provider all use different currencies. A player may deposit in euros, play through an account denominated in dollars, and later withdraw funds back to a bank account in pounds.
Understanding how Currency Conversion Can Affect Casino Transactions makes these situations much easier to follow.
Exchange rates, conversion spreads, card issuer fees, processing dates, and payment-provider charges can all change the final amount received or charged, even when the original casino transaction itself stays exactly the same.
Why Currency Matters at Online Casinos
Every online casino account normally operates in one or more supported currencies.
A player might fund an account using USD while their bank card is denominated in EUR. If the casino or payment processor accepts only USD, the transaction must usually be converted somewhere along the payment chain.
That conversion may be performed by the casino, payment processor, card network, bank, or digital wallet.
Each option can produce a slightly different final amount because providers may use different exchange rates and fees.
This means a $100 casino deposit does not necessarily cost every international player the same amount in their home currency.
How Exchange Rates Change Deposit Costs
An exchange rate determines how much one currency is worth in another.
Imagine a player wants to deposit $100 into a casino account while their bank balance is held in euros.
If the applicable exchange rate is:
1 USD = 0.90 EUR
the theoretical cost would be:
$100 × 0.90 = €90
However, payment providers do not always use the exact benchmark or mid-market exchange rate visible on financial websites.
Mastercard notes that its conversion calculator provides an indicative card-network rate and that an issuing bank may apply additional fees. The rate can also depend on when the transaction is authorized or processed.
That timing can make a noticeable difference when exchange rates move quickly.
Exchange Rate Spread Can Be a Hidden Cost
A provider can make currency conversion more expensive without displaying a separate line called “conversion fee.”
Instead, it may offer an exchange rate slightly worse than the market reference rate.
This difference is commonly called an exchange-rate spread or markup.
For example, imagine the market rate suggests that $100 should cost €90, but the provider’s rate converts the same amount into €93.
The additional €3 is effectively part of the conversion cost.
Wise explains that currency services may apply spreads above the underlying market rate and that comparing the offered rate with a benchmark can help reveal the markup.
This is why players should compare the final converted amount, not only visible fees.
Foreign Transaction Fees Can Add Another Charge
Currency conversion fees and foreign transaction fees are not always the same thing.
A card issuer may impose an additional charge because a payment involves a foreign merchant or another currency.
For example, the U.S. Consumer Financial Protection Bureau notes that foreign transaction charges may be imposed when purchases are made in another currency or with a foreign merchant. It also gives examples where network and issuer charges can combine into a larger total fee.
Suppose a bank charges a hypothetical 3% foreign transaction fee.
If a converted casino deposit equals $200:
$200 × 3% = $6
The player could therefore pay $206 before considering any exchange-rate markup or casino-side processing fee.
Specific fees vary by card and country, so players should check their own card agreement rather than assuming one standard percentage applies everywhere.
Withdrawals Can Trigger Another Conversion
Currency costs do not necessarily end when money reaches the casino.
A withdrawal can create a second currency conversion.
Imagine a player deposits from a euro bank account into a USD casino wallet. The money is first converted from EUR to USD.
Later, the player withdraws the remaining USD balance back to the euro account.
The money may then be converted from USD back to EUR.
That creates two separate FX events:
EUR → USD when depositing
USD → EUR when withdrawing
Each converison can potentially use a different rate or include a separate markup.
If exchange rates changed while the funds were in the casino account, the amount returned in euros could also differ even if the USD balance remained unchanged.
Exchange Rates Can Move Between Deposit and Withdrawal
Foreign-exchange markets constantly change.
Suppose a player converts €900 into approximately $1,000 for a casino account.
Later, the player withdraws exactly $1,000.
If the currency relationship has changed, that same $1,000 might convert into €880, €920, or another amount depending on the rate available at that time.
The difference does not necessarily mean the casino charged a fee.
Part of it can simply come from currency movement.
Card networks also clarify that a transaction may use the exchange rate available when it is authorized or processed rather than necessarily the rate visible when the player first clicks the payment button.
For larger transactions, even a small percentage movement can become noticeable.
Payment Wallets May Perform Their Own Conversion
Digital wallets create another possible conversion layer.
A player may fund a wallet in one currency and then use it to pay a casino operating in another.
Some payment services set their own transaction exchange rates.
PayPal, for example, states that when it performs a currency conversion, its transaction rate includes a conversion spread above a base exchange rate. The exact fee structure can depend on the market and type of transaction.
This creates an important practical question:
Who is actually performing the conversion?
It may be the card issuer, wallet, casino processor, or another party.
Allowing multiple providers to convert the same funds can sometimes create unnecessary costs.
Dynamic Currency Conversion Can Affect the Rate
Dynamic Currency Conversion, or DCC, is another concept players may encounter in cross-border payments.
DCC allows a merchant or payment interface to present a transaction in the cardholder’s home currency rather than the merchant’s local currency.
That sounds convenient because the player immediately sees a familiar amount.
However, convenience does not mean the rate is automatically cheaper.
Visa states that DCC offers should disclose the exchange rate and additional markup or fees, and customers should be given the choice to accept or decline the conversion.
If a payment system provides multiple currency options, players should compare the total converted cost instead of assuming home-currency billing is the cheapest option.
A Simple Example of Multiple FX Costs
Imagine a player wants to deposit the equivalent of $500.
At the benchmark rate, the transaction might equal €450.
Suppose the payment provider’s exchange-rate spread increases the converted amount to €458.
The card issuer then applies a hypothetical 2% international transaction fee:
€458 × 2% = €9.16
The effective cost becomes:
€458 + €9.16 = €467.16
The advertised casino deposit is still $500, but the player’s actual local-currency cost is now considerably higher than the original benchmark conversion.
This example is simplified, but it shows why exchange rate, spread, and transaction fee should be considered seperately.
How Players Can Compare Currency Costs
The most useful number is usually the final amount charged or received.
Before confirming a transaction, compare the casino amount with the amount shown by the bank, card network, or payment provider.
Card networks such as Visa and Mastercard provide currency conversion calculators that can help users estimate cross-border transaction values.
Also check whether your card charges foreign transaction fees and whether your payment wallet applies its own FX spread.
If a casino supports your home currency directly, that may reduce the number of conversions, although it does not guarantee that every possible fee disappears.
Keeping transaction records can also help identify where an unexpected difference occurred.
Understanding how Currency Conversion Can Affect Casino Transactions means looking beyond the deposit or withdrawal amount shown on screen.
Exchange-rate spreads, card fees, payment-provider charges, timing, and repeated conversions can all change the final cost.
Before making an international casino transaction, compare the currencies involved, identify who performs the conversion, and review the final amount before confirming the payment.
